ServicesBobtail Insurance
Non-Trucking Liability (Bobtail) Insurance in Union City
If you're leased on to a motor carrier, their policy covers you under dispatch. Off dispatch, you need your own liability. We put non-trucking liability on paper with the limit and price, explain where it stops, and send the certificate your carrier asks for.
What non-trucking liability covers, and what it doesn't
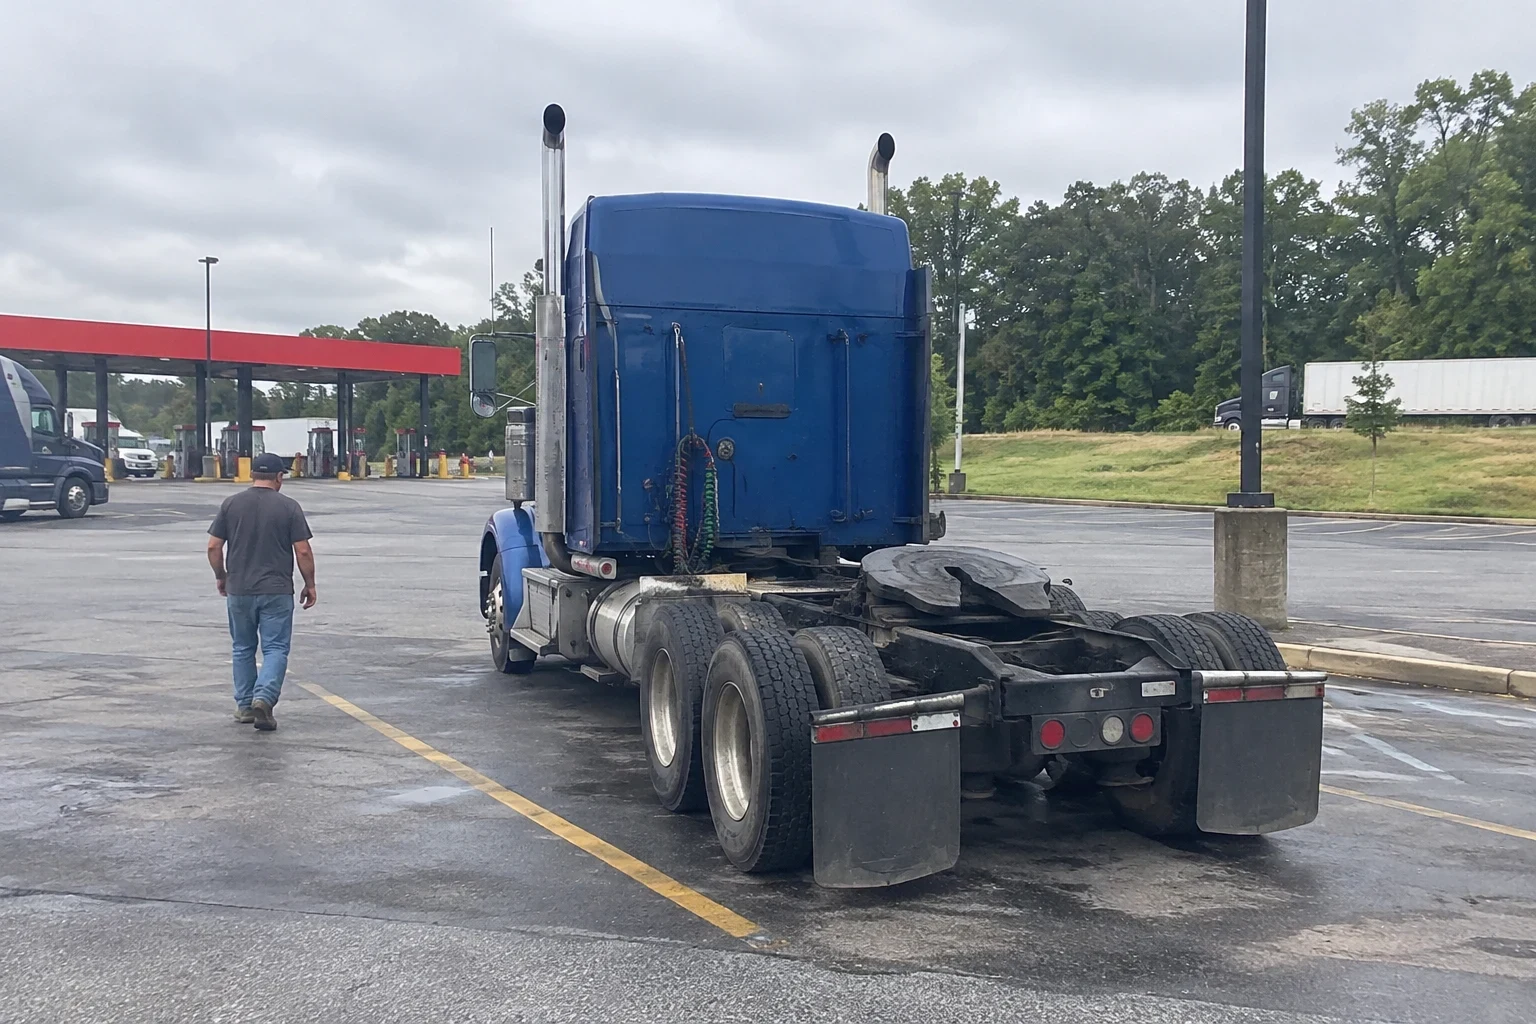
When you're hauling under a motor carrier's authority, their primary auto liability protects you on the load. The gap starts when you're off the clock. Driving to the shop, heading home after a run, grabbing lunch with the tractor. That's where non-trucking liability comes in. It pays for injuries or damage you cause to others while the truck is being used for personal, non-business reasons.
People call it bobtail insurance because most of that driving happens without a trailer. But the two terms aren't always the same thing on paper. Some policies cover you whenever you're not under dispatch, trailer or no trailer. Others are written only for bobtailing. We read the wording with you so you know which one you're buying.
This policy is for owner-operators leased to a carrier. If you run under your own MC authority, you need primary liability instead, and we can talk through that on our Owner-Operator Truck Insurance page or the same phone call.
What you get when we write your policy
- Liability while off dispatch
- Coverage for bodily injury and property damage to others when you're driving the truck for personal use, not hauling for anyone.
- A quote you can read line by line
- We put the limit, the premium and the main exclusions in writing before you decide. Nothing gets added at signing that wasn't on paper first.
- Lease agreement check
- Your lease spells out the limit your carrier requires and whether they need to be named on the policy. We match the coverage to those terms so your onboarding doesn't stall.
- Certificate of insurance for your carrier
- Once the policy is bound, we send the certificate to your carrier with them listed the way the lease asks. If you switch carriers, we update it.
- Help with related coverage
- Many leased drivers also carry Physical Damage Insurance on the tractor. We can price both together so you see the full picture.
Signs you need bobtail coverage
Your carrier asked for proof
Most lease agreements require non-trucking liability before your first load. No certificate, no dispatch.
You're about to sign a lease
Get the coverage lined up before your start date. Waiting until orientation day costs you loads.
You drive the truck home
If the tractor goes home with you, or to the shop, or anywhere off a load, that driving isn't under your carrier's policy.
Your carrier deducts it from settlements
Some carriers offer their own policy and take it out of your pay. That can be fine, but it's worth comparing the limit and price against a policy you own and keep when you leave.
You're not sure what your policy says
If you can't tell whether you have true bobtail or full non-trucking coverage, call and we'll read it with you.
What moves the price
Non-trucking liability usually costs less than primary liability because it covers less driving. Still, the premium depends on you and your truck. Here's what the insurer looks at, and we spell each one out in writing for you.
Liability limit
Higher limits cost more. Your lease usually sets the minimum, so we start there.
Your driving record
Tickets, accidents and years of CDL experience all count. A clean record helps.
Where the truck is garaged
Insurers price by location. Parking in Union City rates differently than a rural county.
Truck type and use
The tractor's age and type matter, and so does how much personal driving you actually do.
Claims history
Past liability claims raise the premium for a few years.
How it works with us
- 1
Phone or video call
We ask about your truck, your driving record, where the truck is parked and who you're leased to. It usually takes one conversation.
- 2
Look at the lease
Send us the insurance section of your lease. We note the required limit and how your carrier wants to be listed.
- 3
Written quote
You get the coverage, the limit, the premium and what's excluded, all in writing. Ask anything. We'll answer it plainly.
- 4
Bind and send the certificate
When you say go, we bind the policy and get the certificate of insurance to your carrier so you can start hauling.
Bobtail insurance questions
Is bobtail insurance the same as non-trucking liability?
Not always. Non-trucking liability covers you any time you're off dispatch. True bobtail coverage is written for driving without a trailer, and some versions apply even under dispatch. Your policy wording decides it, and we show you that wording before you buy.
Does it cover me when I'm heading to pick up a load?
Usually no. Once you're dispatched or driving for business, your carrier's primary liability should apply. Non-trucking liability is for personal use only.
Does it pay for damage to my own truck?
No. It covers damage and injuries you cause to other people. For your tractor, you need physical damage coverage, which we can price at the same time.
I have my own authority. Do I need this?
No. With your own MC authority, your primary liability covers the truck all the time. Non-trucking liability is for drivers leased to someone else's authority.
What happens if I change carriers?
Your policy can usually stay in place. We send a new certificate to the new carrier with them listed the way their lease asks.
Get your bobtail coverage lined up
Tell us who you're leased to and what the lease requires. We'll put the numbers in writing so you know exactly what you're paying for.