ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Union City
Cargo coverage pays when the freight you are hauling gets damaged, stolen or lost. We set the limit to match your broker contracts, check what you actually haul against the exclusions, and put it all in a written quote you can read before you buy.
What cargo insurance does for you
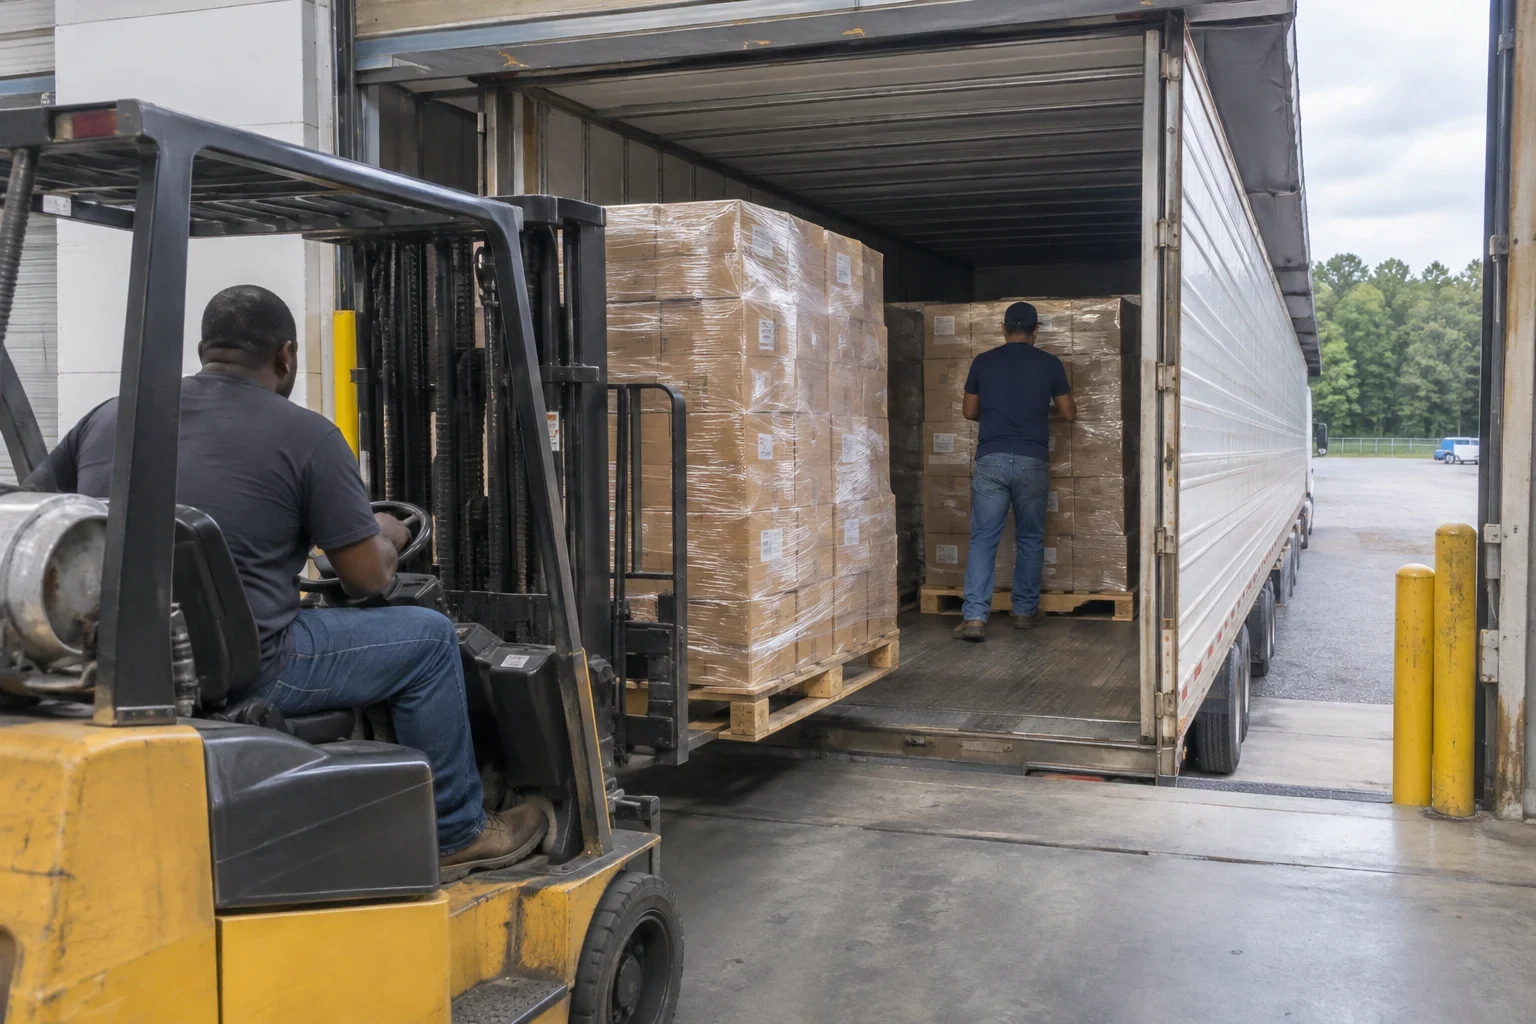
Your auto liability pays for damage you do to other people. It does not pay for the load behind you. Motor truck cargo insurance covers the shipper's freight while it is in your care, from the dock to delivery. Without it, a rollover or a stolen trailer can leave you owing the full value of the load.
Most brokers and shippers will not tender a load until they see a certificate of insurance showing cargo coverage at the limit they ask for. Many carriers out of Union City run freight for several brokers at once, and each one may want something a little different.
The catch with cargo policies is the fine print. Commodity lists, theft conditions and reefer rules decide whether a claim gets paid. We read those parts with you and write them down plainly, so you know what is covered and what is not before a claim ever comes up.
What we set up on a cargo policy
- A limit that fits your loads
- We look at the highest-value load you haul and what your broker agreements require. Then we set the per-load limit so you are not short on the one load that matters.
- Commodity review
- Many policies exclude or cap certain freight, like electronics, alcohol, tobacco or pharmaceuticals. We match your real commodities to the policy wording and flag anything that is left out.
- Reefer breakdown coverage
- If you pull a reefer, spoiled product from a unit failure is often excluded unless you add it. We tell you plainly whether an option includes it.
- Theft conditions
- Some policies only pay on theft if the truck was locked, attended or parked in a secured lot. We show you those conditions in writing so you can plan your stops around them.
- Certificates for brokers
- Once you are covered, we issue certificates of insurance to your brokers and shippers with the right names and limits on them.
Signs your cargo coverage needs a look
A broker asked for a higher limit
If a new broker wants more cargo coverage than you carry, you either raise the limit or pass on the freight. We can price both ways so you can compare.
You started hauling something new
A switch from dry van general freight to beverages, metals or produce can fall outside your current commodity list. Check before the first load, not after a claim.
You added a reefer or a new trailer
New equipment can change what the policy covers and what it costs. A reefer often needs its own endorsement.
You are not sure what is excluded
If you have never read the exclusions page, you are not alone. That is usually where denied claims start.
A claim was denied or paid short
A short payment usually traces back to a limit, a deductible or a condition. We can walk through your policy and find a better fit going forward.
What moves the price of cargo coverage
Cargo premiums come down to how likely a claim is and how big it could get. We list each of these factors in writing for you, so you can see why one option costs more than another.
What you haul
High-theft and high-value freight costs more to cover. So does product that spoils or breaks easily.
Limit and deductible
A higher per-load limit raises the premium. A higher deductible can bring it down, as long as you could cover that amount out of pocket.
Equipment
Reefers, flatbeds and dry vans carry different risks. Reefer breakdown coverage adds to the cost but closes a common gap.
Experience and loss history
A new MC authority or past cargo claims usually means a higher rate. Clean years on the road help.
Where you run
Long-haul lanes and overnight parking in high-theft areas can push the price up compared with local runs.
How we set up your cargo coverage
- 1
Start with a phone call
Tell us what you haul, your equipment, where you run and which brokers you work with. We can talk by phone, by video or at our office.
- 2
We gather the details
We ask for your DOT number, MC authority, loss runs if you have them, and any broker contract terms on cargo limits.
- 3
We shop the market
We take your operation to carriers that write cargo for your type of freight. Each one sees the same commodity list and equipment, so the numbers compare fairly.
- 4
You get it in writing
Your quote lists the limit, deductible, premium, covered commodities, exclusions and any endorsements like reefer breakdown. No add-ons show up later that you did not see first.
- 5
Bind and send certificates
Once you choose, we bind coverage and send certificates of insurance to your brokers so you can start booking loads.
Motor truck cargo insurance questions
Doesn't my liability policy already cover the load?
No. Primary Auto Liability Insurance pays for injuries and damage you cause to others. The freight in your trailer needs its own cargo coverage. Most brokers require both.
How much cargo coverage do I need?
Start with the most valuable load you regularly haul, then check your broker contracts. Many set a minimum, and some ask for more on certain freight. We help you pick a limit that covers both.
Is theft covered?
Usually, but often with conditions. Some policies need the truck locked, the keys removed, or the trailer parked in a secured lot. We point those terms out in writing before you buy.
I'm leased on to a carrier. Do I need my own cargo policy?
Sometimes. Many carriers cover cargo for their leased owner-operators, but not all do, and some pass the deductible to you. Check your lease agreement, and we can go over it with you.
Will spoiled reefer loads be paid?
Only if your policy includes reefer breakdown coverage. Without it, spoilage from a unit failure is often excluded. We show whether it is included before you sign.
Can you add a broker to my certificate?
Yes. Once your policy is active, we issue certificates of insurance to your brokers and shippers with the names and limits they ask for.
Know what your cargo policy covers
Tell us what you haul and who you haul for. We will put the limit, deductible, exclusions and premium in writing so you can decide with the facts in front of you.