ServicesCommercial Trucking Insurance
Commercial Trucking Insurance in Union City
We put together the coverage a motor carrier needs to run legally and stay protected: liability, physical damage, cargo and the filings tied to your DOT number. You get every piece and every price factor in writing before anything is bound.
One Policy Package Built Around How You Haul
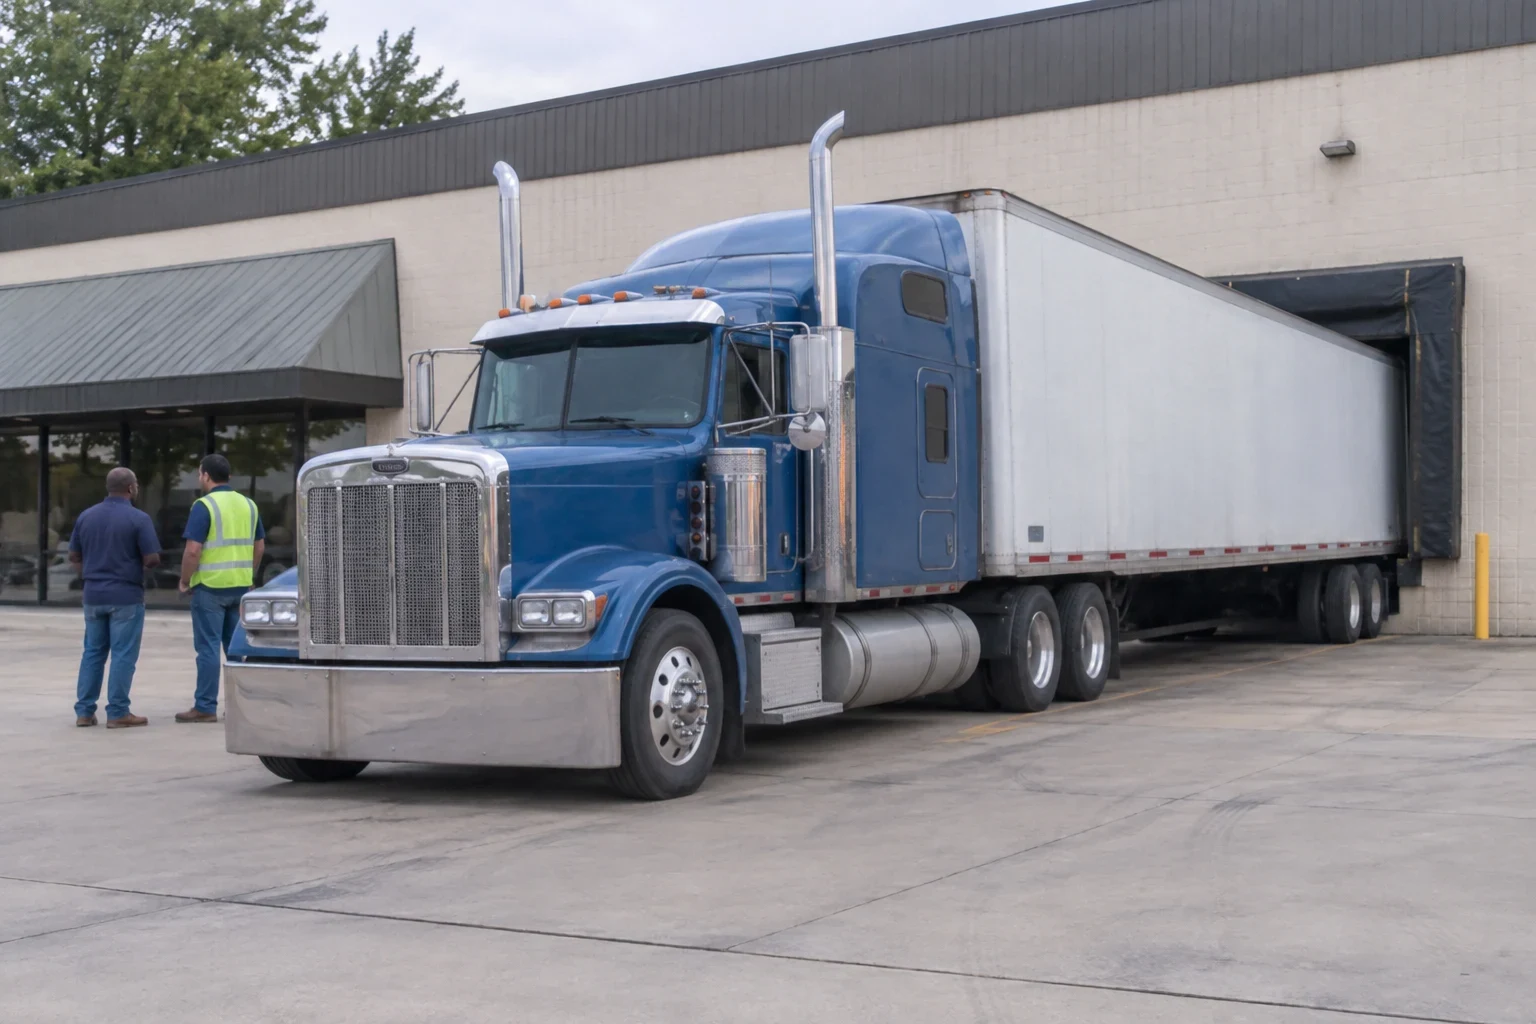
Commercial trucking insurance is not one policy. It is a set of coverages that fit together: primary auto liability for damage you cause on the road, physical damage for your own truck and trailer, motor truck cargo for the freight, and add-ons like trailer interchange or non-trucking liability when your setup calls for them.
Which pieces you need depends on your operation. A leased owner-operator, a new authority hauling general freight and a dump truck outfit working local job sites all need different things. We ask how you run, then build the package from there.
Before you commit, we lay out each coverage, its limit, its deductible and what drives its premium on paper. If a line is optional, we say so. If something is missing that a broker or shipper will ask for, we flag it.
What We Put Together for You
Primary auto liability
Covers injuries and property damage you cause to others while driving under your authority. It is the coverage federal and state rules require, and the one brokers check first.
Physical damage
Pays to repair or replace your own tractor, truck or trailer after a wreck, fire, theft or weather damage. If you finance or lease the equipment, the lender will usually require it.
Motor truck cargo
Protects the load you are hauling. We match the limit to what you actually carry and point out exclusions that matter for your freight, like reefer breakdown or unattended vehicles.
Filings for your authority
We handle the insurance filings tied to your DOT number and MC authority so your carrier status stays active.
Certificates of insurance
Brokers and shippers want a certificate of insurance before they hand you a load. We issue them and add certificate holders when you need it.
Add-on coverages
Trailer interchange, non-trucking liability (bobtail) and general liability get added only when your contracts or setup call for them.
Signs It Is Time to Look at Your Coverage
You are getting your own authority
Leaving a lease to run under your own MC number means your own liability and filings. Your authority will not go active without them.
A broker turned down your certificate
If a broker says your limits are too low or your cargo coverage does not fit their freight, you are losing loads. That is a fixable problem.
Your renewal jumped with no clear reason
A big premium increase with no explanation is worth a second look. We will show you what is driving the number.
You added a truck, driver or trailer
New equipment and new drivers have to be listed. An unlisted unit can leave you uncovered at the worst moment.
You changed what or where you haul
Switching freight types, going from local to over-the-road or adding hazmat changes your risk and your coverage needs.
How Getting Covered Works
- 1
Talk it through
Call us or set up a video meeting. We ask about your trucks, drivers, freight, radius and any loss history. Have your DOT number and VINs handy if you can.
- 2
We shop the coverage
We take your details to the carriers we work with and look for coverage that fits your operation, not just the lowest number.
- 3
You get it in writing
We send a written quote showing each coverage, limit, deductible and premium. We walk through it with you and answer every question.
- 4
Bind, file and issue certificates
Once you say yes, we bind the policy, make your filings and send certificates to your brokers so you can get rolling.
What Moves Your Premium
Trucking premiums swing a lot from one carrier to the next. Most of it comes down to a handful of factors, and we show you which ones are driving your number. Nothing gets added after you approve the quote.
- Driver records and experience
- Years of commercial driving, MVR history and CDL experience carry a lot of weight. A newer driver or a recent violation raises the price.
- Authority age and loss history
- A brand-new MC number costs more to insure than one with a clean track record. Past claims stay on your loss runs for years.
- Freight and radius
- What you haul and how far you go both matter. Local runs around the airport and the interstates through Union City price differently than long-haul freight across several states.
- Equipment value and type
- The stated value of your trucks and trailers sets your physical damage premium. Dump trucks, reefers and flatbeds each carry their own risks.
- Limits and deductibles
- Higher liability or cargo limits cost more. A higher deductible lowers premium but means more out of pocket on a claim.
Commercial Trucking Insurance Questions
Something not covered here? (770) 790-4033
What coverage do I need just to keep my authority active?
At minimum, primary auto liability with the filing tied to your DOT number. Most brokers will also want cargo coverage before they give you freight. Physical damage is usually required if your truck is financed.
Can I insure just one truck?
Yes. A lot of the operators we work with run a single truck. The coverage pieces are the same as a fleet, just sized to one unit and one driver. Our Owner-Operator Truck Insurance page goes into more detail.
How fast can I get a certificate of insurance?
Once a policy is bound, we can issue certificates to your brokers and shippers. The timing depends on the carrier and how quickly we get your documents, so we will tell you what to expect when we quote.
Why are trucking insurance quotes so different from each other?
Carriers weigh driver history, authority age, freight and equipment differently. Quotes can also differ in limits, deductibles and exclusions. That is why we put every line in writing, so you are comparing the same things.
Do I need to come to your office?
No. We can do everything by phone or video. If you would rather sit down in person, you are welcome at our office.
See Every Line Before You Sign
Tell us about your trucks and what you haul. We will put the coverage and the price factors in writing so you know exactly what you are paying for.