ServicesFleet Truck Insurance
Fleet Truck Insurance in Union City, GA
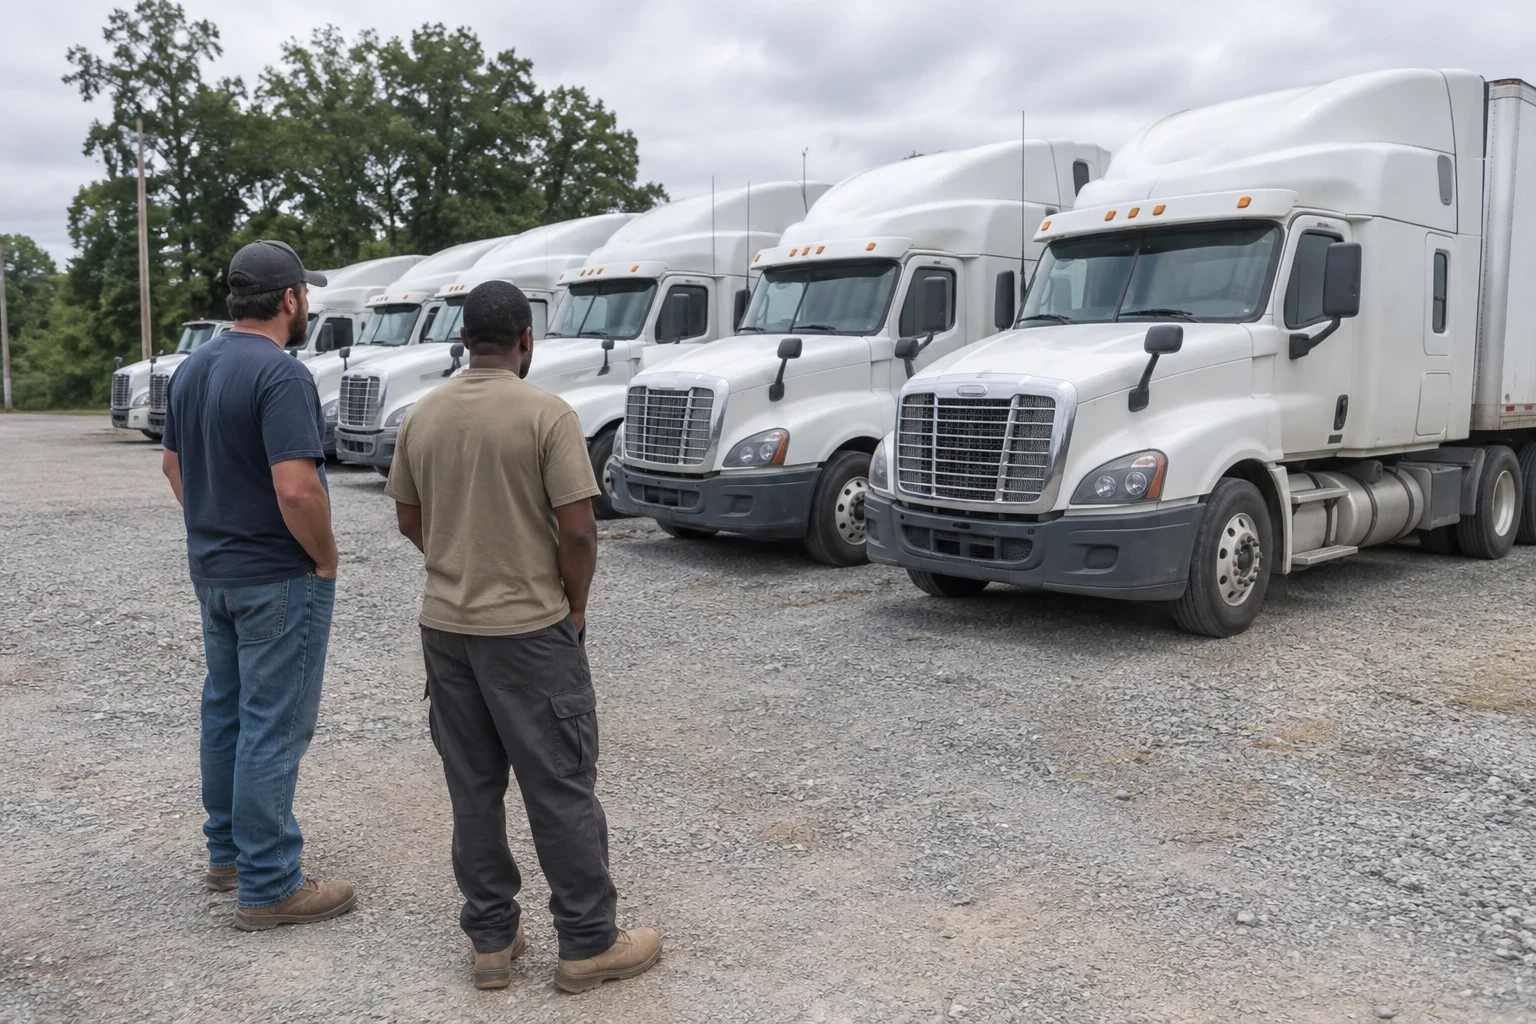
When you run more than a couple of trucks, the policy gets harder to track. We put your whole fleet on paper: every unit, every driver, every limit. You see what each piece costs and why, before anything is bound.
One policy that keeps up with your trucks
Fleet truck insurance covers several power units and drivers under one policy instead of a pile of separate ones. It usually brings together auto liability, physical damage, cargo coverage and any trailer coverage your contracts call for. One renewal date. One set of filings tied to your DOT number and MC authority.
Fleets change. You buy a truck, sell one, hire a driver, lose one. A good fleet policy has a clean way to add and drop units, and a schedule you can read without calling us every time a broker asks.
Our way of working is simple. Before you buy, you get a written quote that lists each truck, each driver and each coverage line with its limit and deductible. If a number changes later, you hear why from us first.
What we set up on a fleet policy
- 01
Primary auto liability
The coverage the FMCSA and your shippers check first. We match limits to what your contracts and filings require, not just the legal floor.
- 02
Physical damage by unit
Each truck and trailer is listed with its stated value and deductible. Older units can carry different terms than newer ones, so you are not paying full freight on a truck worth half what it was.
- 03
Cargo coverage for what you haul
We write the commodities you actually move. If you haul reefer loads, we look at spoilage and breakdown terms, because that is where cargo claims often get denied.
- 04
Driver schedule
Every driver goes on the list with their record checked. You know before binding which drivers are accepted and which ones raise the premium.
- 05
Filings and certificates
We handle the federal and state filings for your authority and issue a certificate of insurance when a shipper, broker or yard asks for one.
- 06
Add-ons when the work calls for it
Trailer interchange, non-trucking liability for leased drivers, or general liability for your yard. Only if your operation needs it, and each one priced on its own line.
Questions about Fleet Truck Insurance?
Call(770) 790-4033Signs it is time to move to a fleet policy
Renewals on different dates
If your trucks renew in different months, you are juggling paperwork and probably missing a better rate on a combined policy.
Brokers keep asking for updated certificates
When every new unit means a scramble for a fresh certificate of insurance, your setup is too loose for the size you are.
Your premium jumped and nobody explained it
A fleet policy built line by line shows where the cost comes from. If you cannot point to the truck or driver behind the increase, something is off.
You added drivers this year
New hires change your risk. If they were added in a hurry, it is worth checking that each one is actually listed and accepted.
A contract asks for higher limits
Bigger shippers often want more liability or cargo coverage than you carry now. Better to set that up before the load, not after.
How we price and set up your fleet
- 1
First call
You tell us how many trucks you run, what you haul and how far. We tell you what we need to price it. Takes about as long as a fuel stop.
- 2
Gather the paperwork
Usually your unit list with VINs and values, your driver list, and loss runs from your current insurer. Bring it by our office, or we can go over it together by phone or video.
- 3
Line-by-line pricing in writing
You get a written breakdown that shows each truck, each driver, each coverage and its cost. We walk you through it and point out anything that looks high or thin.
- 4
Bind and file
Once you sign off, we bind coverage, make your filings and send certificates to anyone who needs them. During the term, call us to add or drop a unit and we confirm the change in writing.
What moves the cost of fleet coverage
Fleet pricing is built from the ground up. Each truck and each driver adds to the total, and your history as a motor carrier shapes the rate on all of it. We show these pieces on paper up front so nothing shows up later as a surprise.
- Number and value of units
- More trucks means more premium, and higher-value trucks cost more to cover for physical damage. Stated values that match the real market keep this fair.
- Driver records and experience
- Violations, accidents and years behind the wheel all count. One driver with a rough record can move the price of the whole policy.
- Loss history and safety scores
- Your past claims and your CSA scores tell insurers how you run. A clean few years helps at renewal.
- Radius and freight
- Local work around the south metro prices differently than long-haul runs across several states. What you haul matters too, especially high-value or temperature-sensitive loads.
- Limits and deductibles
- Higher limits cost more. Higher deductibles cost less up front but mean more out of pocket on a claim. We show you both sides.
Fleet truck insurance questions
Can I add a truck in the middle of the policy term?
Yes. Call us with the VIN, value and who will drive it. We add it, tell you the change in premium, and confirm it in writing. If a broker needs proof right away, we send an updated certificate.
What happens if one of my drivers has a bad record?
The insurer may charge more, add terms, or decline that driver. We tell you before you bind which way it went. Then you can decide whether to keep that driver on the policy.
Do all my trucks have to be the same type?
No. Plenty of fleets run a mix, like tractors with box trucks or dump trucks. Each unit gets rated for how it is used. If part of your fleet does construction hauling, we look at that work separately.
Why do you need my loss runs?
Loss runs show your claims history with past insurers. Without them, most companies will not give a firm number. You can request them from your current insurer, and we can tell you what to ask for.
Can I switch before my current policy renews?
Usually, yes. We line up the new coverage so it starts the day the old one ends, with filings in place, so your authority never shows a gap. We also check for any cancellation terms on your current policy first.
See your whole fleet on one page
Have your truck list and driver list handy. We will go through it with you and put every line in writing before you decide.