Union City, GA
Trucking Insurance in Union City With Every Cost on Paper
We set up primary liability, physical damage, cargo coverage and bobtail for owner-operators, new MC authorities, fleets, hotshot, box truck and dump truck outfits. Carriers in Union City, Fairburn and East Point see each coverage, limit, deductible and premium in writing before anything is bound.
- Licensed for property and casualty insurance
- In business 5 years
- Every line priced on paper
- Office, phone or video
Coverage for Every Kind of Truck Operation
Most trucks need the same core pieces: primary auto liability, physical damage on the unit and motor truck cargo for the load. From there it depends on how you run. Leased-on drivers need non-trucking liability (bobtail), and carriers pulling someone else's trailer need trailer interchange. New authorities, fleets, hotshot rigs, box trucks and dump trucks each have their own pages below, so you can read about the setup that fits your operation.
Commercial Trucking Insurance
Liability, physical damage, cargo and the filings your authority needs, built around how your trucks run and quoted line by line before you sign.
Primary Auto Liability
Liability coverage and FMCSA filings for motor carriers, with limits, endorsements and premium factors laid out in writing before you sign.
Physical Damage Insurance
Coverage for your truck and trailer after a wreck, fire, theft or storm, with the stated value and deductible spelled out before you sign.
Motor Truck Cargo Insurance
Coverage for the freight on your truck, with the limit, deductible and commodity exclusions spelled out in writing before you sign.
Bobtail Insurance
Liability coverage for leased owner-operators when the truck is off dispatch, priced in writing so you can see the limits and the exclusions before you sign.
Trailer Interchange Insurance
Physical damage coverage for trailers you pull but don't own, set up to match the limits your interchange agreement asks for.
Owner-Operator Insurance
Coverage for one-truck operations, leased on or running your own MC authority, with limits, deductibles and price factors listed in writing.
New Authority Truck Insurance
Coverage and federal filings for carriers just getting their MC authority, priced in writing so you know each line before you sign.
Fleet Truck Insurance
One policy for your trucks and drivers, with each unit, limit and deductible listed in writing so you can see exactly what you pay for.
Dump Truck Insurance
Coverage for dump trucks, tri-axles and construction haulers, with your haul radius, materials and limits laid out in writing line by line.
Hotshot Truck Insurance
Coverage for one-ton pickups and gooseneck or flatbed trailers, with liability, cargo and physical damage priced line by line before you sign.
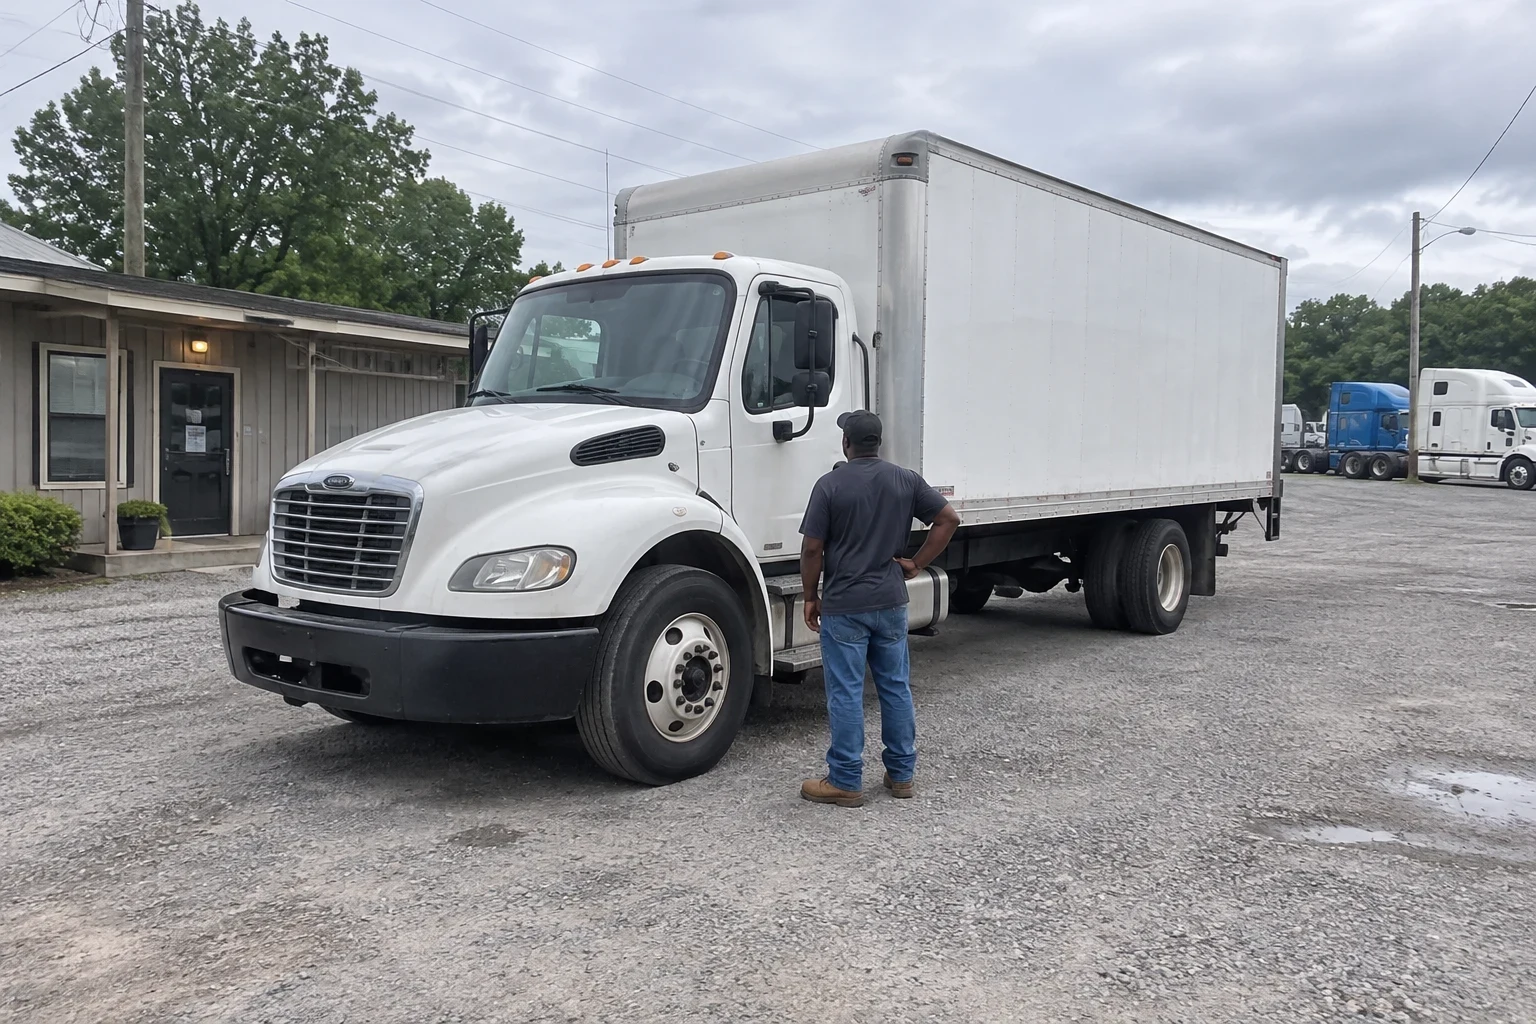
Box Truck Insurance
Liability, cargo and physical damage for 16 to 26 foot box trucks, with each coverage and premium listed separately in writing.
Why Truckers Get Their Coverage Here
We keep it simple. You see what each line covers and what it costs, and nothing gets added after you sign.
Everything on paper first
Every proposal comes broken out by coverage: limit, deductible and premium for each piece. You can read it, compare it and ask about any line before you commit. If a cost is part of the deal, it is on the page.
Licensed for property and casualty insurance
We hold a property and casualty license, which is the license that covers commercial auto and trucking policies. That means we can price and place the coverage your MC authority and your shippers expect.
Five years in this line of work
We have been in business 5 years. In that time we have learned which questions a carrier asks when a load is held up waiting on a certificate of insurance, and we answer them straight.
We explain, we don't upsell
If you run local dump work, you may not need the same cargo limit as a reefer hauler going coast to coast. We tell you what is required, what is optional and what we think is worth it. You decide.
Filings and certificates handled
Once a policy is bound, we take care of the insurance filings tied to your DOT number and send certificates of insurance to the brokers and shippers you name.
What Moves Your Trucking Insurance Premium
There is no flat price for truck insurance. Two drivers with the same truck can get very different numbers. Here is what the carriers look at, so the price makes sense when you see it.
We gather your details, shop the coverage with carriers and send you a breakdown that shows each line and its cost. Nothing changes between that breakdown and the policy unless you ask for it.
- Driving records
- Moving violations, accidents and CDL experience for every listed driver. A clean MVR with a few years of CDL time helps more than almost anything else.
- How long you have had authority
- A brand new MC authority has no track record, so carriers price in more risk. Premiums usually ease as you build clean years under your own DOT number.
- Radius and lanes
- Local work inside a short radius rates differently than long-haul runs through several states. Where you go and how far matters.
- What you haul
- General freight, building materials, refrigerated goods and higher-value loads all carry different cargo risk. The commodity list drives your cargo premium.
- Truck value and type
- Physical damage is priced on what the tractor, box truck or trailer is worth. Older paid-off units sometimes carry liability only, which changes the total.
- Limits, deductibles and loss history
- Higher limits cost more, higher deductibles cost less. Prior claims on your loss runs will show up in the rate.
Carriers We Work With Around Union City
We're based in Union City, GA and work with motor carriers across the south side of the metro. That includes South Fulton, Fairburn, Palmetto, East Point, College Park, Hapeville and Riverdale, plus Tyrone, Peachtree City and Douglasville.
- Union City
- South Fulton
- Fairburn
- East Point
- Riverdale
- College Park
- Tyrone
- Hapeville
- Palmetto
- Peachtree City
- Douglasville
Since most of the work happens by phone or video, being outside these towns isn't a problem. Give us a call and we'll tell you if we can help.
A Small Shop That Works With Truckers
Trucking Insurance Union City is a small agency working with owner-operators, new carriers and small to mid-size fleets. We work from our office and by phone and video, so you don't have to park the truck to get a quote.
We started this business on one idea: a trucker should see exactly what he's paying for before he pays it. That's why every proposal we send is spelled out coverage by coverage, and why we take the time to explain bobtail, interchange and cargo terms in plain words.
When renewal comes around, we look at the policy with you again. If you added a truck, dropped a lane or picked up a new commodity, we check whether the coverage still fits before anything rolls over.
- License
- Licensed for property and casualty insurance
- In business
- In business 5 years
Questions Truckers Ask Us
Something not covered here? (770) 790-4033
How much does truck insurance cost?
It depends on your drivers, your authority age, what you haul, your radius and the value of your trucks. We can't give a fair number until we know those details. Once we do, you get a breakdown with each coverage priced out.
What do I need to have ready for a quote?
Your DOT number and MC number if you have them, CDL info for each driver, VINs for your trucks and trailers, and loss runs from any prior insurance. A rough idea of your lanes and commodities helps too. If something is missing, we can still start.
Can you insure a brand new MC authority?
Yes. New authority truck insurance is a big part of what we do. Premiums tend to run higher in the first years, and we explain why up front so you're not caught off guard. We also handle the filings your authority needs to go active.
What's the difference between primary liability and bobtail?
Primary auto liability covers damage you cause to others while operating under your own authority or under dispatch. Non-trucking liability, often called bobtail, covers a leased owner-operator when the truck is used for personal reasons off dispatch. The motor carrier you're leased to usually carries the primary policy.
Do you work with owner-operators leased to a carrier?
Yes. Leased-on drivers usually need bobtail and physical damage on their own truck, and sometimes more depending on the lease. Bring us a copy of your lease agreement. We read what the motor carrier provides and set up only what fills the gaps.
Will there be fees added after I sign?
No. Policy fees, taxes and anything else that's part of the cost are on the paperwork you see before you sign. If you change coverage later, we write up the change and the new cost before it takes effect.
How do I get a certificate of insurance to a broker or shipper?
Give us the name and contact details of the broker or shipper. We send the certificate of insurance once your policy is in force. If they need specific wording or limits shown, tell us and we'll check what your policy supports.
Do I have to come into the office?
No. Most of our customers work with us entirely by phone and video. You're welcome at our office in Union City if you prefer to talk in person.
How Getting Covered Works
Most of this happens by phone or video. You can also stop by our office if you'd rather sit down.
- 1
Talk through your operation
We ask what you drive, what you haul, how far you run and who drives. Short call, no pressure.
- 2
Send us the basics
Usually your DOT number, MC number if you have one, CDL details for each driver, VINs and any prior loss runs. If you're still waiting on authority, we start with what you have.
- 3
Go over the numbers
We lay out each coverage with its limit, deductible and premium, in writing. Then we walk through it with you line by line and clear up anything that reads like fine print.
- 4
Bind and get on the road
When you say yes, we bind the policy, handle the filings and send your certificate of insurance where it needs to go.
Ready to See Your Numbers?
Tell us about your trucks and your loads. We'll lay out every coverage and what it costs, so you know the full price before you commit.